We can remember minutely and precisely only the things which never really happened to us.
Eric Hoffer, “Thoughts of Eric Hoffer”, New York Times Magazine, 1971-04-25.
November 14, 2019
QotD: Memory
Comments Off on QotD: Memory
July 9, 2019
The main economic damage of Brexit is the extended period of uncertainty
At the Continental Telegraph, Tim Worstall interprets a recent Bank of England recommendation to really mean “do Brexit” and “get it over with”:
“The bank of England. London.”by Demetrio Neri_1959 is licensed under CC BY-NC-SA 2.0


To pull that out of the jargon, when every bugger’s running around screaming because they don’t know what’s going to happen then things are dark for the long term future of the economy. Just because the screaming and the running around means no bugger is doing anything else.
And here’s the thing – that lookin’ dark bit gets worse the longer the uncertainty lasts. To the point that the effect just of the not knowing becomes greater than the possible effect of any particular event in that universe of possibilities. It really is true that continuing to delay Brexit will, at some point, become worse than any particular Brexit outcome.
Thus get on with it, get it done. And given that we’ll get something of a bloody revolution if the Remainers win – we Brits being really quite keen on this democracy idea, we get to choose not they – then the getting on with it will have to be to leave. Yesterday would have been good, tomorrow if that’s not possible.
Comments Off on The main economic damage of Brexit is the extended period of uncertainty
July 11, 2018
Environmentalists against science
At Catallaxy Files, Jeff Stier looks at situations when activists who normally fetishize their devotion to science will go out of their way to fight against scientific findings that don’t co-incide with their preferences:
The debate over regulation often devolves into a debate about “too little” versus “too much” regulation, split along the ideological divide. Too little regulation, goes the argument, and we are exposed to too much risk. Too little, and we don’t advance.
This binary approach, however, represents the dark-ages of regulatory policy. It was more frequently relevant when our tools to measure risk were primitive, but today’s technology allows much more precise ways to evaluate real-world risks. With less uncertainty, there’s less of a need to cast a broad regulatory net.
Regulation not warranted by countervailing risk just doesn’t make sense. That’s why a pseudoscientific approach, dubbed the “precautionary principle,” behind much of today’s regulation is so pernicious. This dogma dictates that it’s always better to be safe than to ever be sorry. The approach is politically effective not only because it’s something your mother says, but because it’s easier to envision potential dangers, remote as they may be, than potential benefits. Uncertainty, it turns out, is a powerful tool for those who seek to live in a world without risk.
But what happens when regulators can get a reasonably good handle on benefits and risks? Some potential risks have been eliminated simply because the basis for the concern has proven to be unwarranted. For more than two decades, the artificial sweetener, saccharin, came with a cancer warning label in the U.S.But it turned out that the animal experiment which led to the warning was later found to be irrelevant to humans, and the warning was eventually removed.
Warning about a product when risks are not well-understood is prudent. But it would be absurd to continue to warn after the science tells us there’s nothing to worry about.
Today, an analogous situation is playing out in the EU, where activists are using outmoded tests not just to place warning labels on silicones, a building block of our technological world, but to ban them outright.
The playbook is predictable: as the scientific basis for a product’s safety grows, opponents go to increasingly great lengths to manufacture uncertainty, move the goalposts and capitalize on scientific illiteracy to gain the political upper-hand.
We’ve seen these tactics employed in opposition to everything from growing human tissue in a lab, to harm-reducing alternatives to smoking, such as e-cigarettes. Now, the effort to manufacture uncertainty is playing out in the debate over the environmental impact of silicones, which are used to in a wide range of consumer, medical, and industrial products.
Fortunately, in the case of silicones, regulators in a number of countries, including Australia, have put politics aside and adhere to appropriate scientific methods to inform their decision-making.
Comments Off on Environmentalists against science
June 5, 2018
Down with the experts!
In Quillette, Alex Smith explores the limits of expertise and why so many people today would eagerly agree with the sentiments in my headline:
“People are sick of experts.” These infamous and much-derided words uttered by UK Conservative parliamentarian Michael Gove express a sentiment with which we are now probably all familiar. It has come to represent a sign of the times — either an indictment or a celebration (depending on one’s political point of view) of our current age.
Certainly, the disdain for expertise and its promised consequences have been highly alarming for many people. They are woven through various controversial and destabilising phenomena from Trump, to Brexit, to fake news, to the generally ‘anti-elitist’ tone that characterises populist politics and much contemporary discourse. And this attitude stands in stark contrast to the unspoken but assumed Obama-era doctrine of “let the experts figure it out”; an idea that had a palpable End of History feeling about it, and that makes this abrupt reversion to ignorance all the more startling.
The majority of educated people are fairly unequivocal in their belief that this rebound is a bad thing, and as such many influential voices — Quillette‘s included — have been doing their best to restore the value of expertise to our society. The nobility of this ambition is quite obvious. Why on earth would we not want to take decisions informed by the most qualified opinions? However, it is within this obviousness that the danger lies.
I want to propose that high expertise, whilst generally beneficial, also has the capacity in certain circumstances to be pathological as well — and that if we don’t recognise this and correct for it, then we will continue down our current path of drowning its benefits with its problems. In short, if you want to profit from expertise, you must tame it first.
[…]
However, it is worth drawing a distinction between these two types of expertise — the kind people question, and the kind people don’t. In short, people value expertise in closed systems, but are distrustful of expertise in open systems. A typical example of a closed system would be a car engine or a knee joint. These are semi-complex systems with ‘walls’ — that is to say, they are self-contained and are relatively incubated from the chaos of the outside world. As such, human beings are generally capable of wrapping their heads around the possible variables within them, and can therefore control them to a largely predictable degree. Engineers, surgeons, pilots, all these kinds of ‘trusted’ experts operate in closed systems.
Open systems, on the other hand, are those that are ‘exposed to the elements,’ so to speak. They have no walls and are therefore essentially chaotic, with far more variables than any person could ever hope to grasp. The economy is an open system. So is climate. So are politics. No matter how much you know about these things, there is not only always more to know, but there is also an utterly unpredictable slide towards chaos as these things interact.
The erosion of trust in expertise has arisen exclusively from experts in open systems mistakenly believing that they know enough to either predict those systems or — worse — control them. This is an almost perfect definition of hubris, an idea as old as consciousness itself. Man cannot control nature, and open systems are by definition natural systems. No master of open systems has ever succeeded — they have only failed less catastrophically than their counterparts.
Comments Off on Down with the experts!
January 11, 2018
QotD: Regime uncertainty
Washington’s destructive policies have been dubbed “regime uncertainty” in a strand of innovative analyses pioneered by Robert Higgs of the Independent Institute. Regime uncertainty relates to the likelihood that an investor’s private property — namely, the flows of income and services it yields — will be attenuated by government action. As regime uncertainty is elevated, private investment is notched down from where it would have been. This can result in a business-cycle bust and even economic stagnation. I recommend Higgs’ most recent book for evidence on the negative effects of regime uncertainty: Robert Higgs. Taking a Stand: Reflections on Life Liberty, and the Economy. Oakland, CA: The Independent Institute, 2015.
Steve Hanke, “What’s Killing U.S. Growth?”, Huffington Post, 2016-04-12.
Comments Off on QotD: Regime uncertainty
October 5, 2017
Four Reasons Financial Intermediaries Fail
Marginal Revolution University
Published on 26 Jul 2016As we’ve discussed in previous videos, financial intermediaries bridge savers and borrowers. When these bridges crumble, the effects can be disastrous. For businesses, credit shortages can lead to bankruptcy, or layoffs. For individuals, they rely on credit to invest in education or a new home or car. These negative effects show you how crucial intermediaries are to our lives.
Still, what exactly causes failed intermediation? Four answers:
First, insecure property rights. Simply speaking, when you save money at a bank, you expect the ability to pull out your funds when needed. But what if your deposits are frozen? Or confiscated altogether? For instance, in 2013 amidst a financial crisis, the government in Cyprus confiscated bank deposits to help pay down the country’s budget shortfall. You can see how insecure property rights can scare away potential savers.
Second, controls on interest rates. Interest rates are the price of borrowing. Thus, controls on interest rates, often called usury laws, are effectively price ceilings—they set the interest rate lower than the market equilibrium interest rate. With this forced lowering of interest rates, borrowers will want to borrow more, but lenders won’t want to lend. The effect? A lending shortage.
Third, politicized lending. Banks profit by assessing risk, and then loaning, based on that assessment. Banks that excel at assessment succeed. Those poor at it die out. Problems arise when the government intervenes to prop up failing banks, resulting in what we call “zombie banks.” In such cases, intervention undercuts normal competition, and intervention tends to favor banks that are politically connected. In fact, it’s been shown that there’s an inverse correlation between government ownership in banks and a country’s GDP per capita and productivity growth.
Fourth, you have runs, panics, and scandals. Remember, trust is vital to the financial system. When trust erodes, depositors may rush to withdraw their money from banks, causing what is known as a “bank run.” This can cause banks to fail, as we saw during the Great Depression. Scandals can also depress market confidence. Enron, WorldCom and Bernie Madoff may come to mind.
So, which of these four factors contributed to the Great Recession of 2008?
We’ll discuss that in our next video.
Comments Off on Four Reasons Financial Intermediaries Fail
April 2, 2017
The (inevitable) failure of the “Revolution in Military Affairs”
In an article about security incident response automation, Bruce Schneier provides a useful thumbnail sketch of a US Army attempt to dispel the fog of war in real time:
While this is a laudable goal, there’s a fundamental problem with doing this in the short term. You can only automate what you’re certain about, and there is still an enormous amount of uncertainty in cybersecurity. Automation has its place in incident response, but the focus needs to be on making the people effective, not on replacing them security orchestration, not automation.
This isn’t just a choice of words — it’s a difference in philosophy. The US military went through this in the 1990s. What was called the Revolution in Military Affairs (RMA) was supposed to change how warfare was fought. Satellites, drones and battlefield sensors were supposed to give commanders unprecedented information about what was going on, while networked soldiers and weaponry would enable troops to coordinate to a degree never before possible. In short, the traditional fog of war would be replaced by perfect information, providing certainty instead of uncertainty. They, too, believed certainty would fuel automation and, in many circumstances, allow technology to replace people.
Of course, it didn’t work out that way. The US learned in Afghanistan and Iraq that there are a lot of holes in both its collection and coordination systems. Drones have their place, but they can’t replace ground troops. The advances from the RMA brought with them some enormous advantages, especially against militaries that didn’t have access to the same technologies, but never resulted in certainty. Uncertainty still rules the battlefield, and soldiers on the ground are still the only effective way to control a region of territory.
But along the way, we learned a lot about how the feeling of certainty affects military thinking. Last month, I attended a lecture on the topic by H.R. McMaster. This was before he became President Trump’s national security advisor-designate. Then, he was the director of the Army Capabilities Integration Center. His lecture touched on many topics, but at one point he talked about the failure of the RMA. He confirmed that military strategists mistakenly believed that data would give them certainty. But he took this change in thinking further, outlining the ways this belief in certainty had repercussions in how military strategists thought about modern conflict.
McMaster’s observations are directly relevant to Internet security incident response. We too have been led to believe that data will give us certainty, and we are making the same mistakes that the military did in the 1990s. In a world of uncertainty, there’s a premium on understanding, because commanders need to figure out what’s going on. In a world of certainty, knowing what’s going on becomes a simple matter of data collection.
Comments Off on The (inevitable) failure of the “Revolution in Military Affairs”
July 10, 2016
QotD: Science isn’t something you “believe in”
The arguments about global warming too often sound more like theology than science. Oh, the word “science” gets thrown around a great deal, but it’s cited as a sacred authority, not a fallible process that staggers only awkwardly and unevenly toward the truth, with frequent lurches in the wrong direction. I cannot count the number of times someone has told me that they believe in “the science,” as if that were the name of some omniscient god who had delivered us final answers written in stone. For those people, there can be only two categories in the debate: believers and unbelievers. Apostles and heretics.
This is, of course, not how science works, and people who treat it this way are not showing their scientific bona fides; they are violating the very thing in which they profess such deep belief. One does not believe in “science” as an answer; science is a way of asking questions. At any given time, that method produces a lot of ideas, some of which are correct, and many of which are false, in part or in whole.
Megan McArdle, “Global-Warming Alarmists, You’re Doing It Wrong”, Bloomberg View, 2016-06-01.
Comments Off on QotD: Science isn’t something you “believe in”
June 27, 2015
QotD: The corporate tax game
You can think of corporate taxation as a sort of long chess match: The government makes a move. Corporations move in response — sometimes literally, to another country where the tax burden is less onerous. This upsets the government greatly, and the Barack Obama administration in particular. Treasury Secretary Jack Lew has written a letter to Congress, urging it to make it stop by passing rules that make it harder to execute these “inversions.”
I’ve got a better idea: What if we made our tax system so attractive to corporations that they would have no interest in moving themselves abroad?
The problem with this extended chess game is that every move is very costly. First, it adds to the complexity of the tax code. With every new rule — no matter how earnestly said rule attempts to close a “loophole” — it becomes harder to know whether you are in compliance with the law. This is true on both sides; corporate tax law has now passed well beyond the point where it is possible for a single expert to be familiar with its ins and outs. This makes it harder to plan business expansions, harder to forecast government revenue, and it requires both sides to hire more experts in order to determine whether corporations are compliant. It also means more lawsuits, and longer ones, as both sides wrangle over how this morass of laws should be applied to real-world situations.
You can think of it this way: Every new law has possible intersections with every other tax law in existence. As the number of laws grows, the number of possible intersections grows even faster. And each of those intersections represents both a possible way to avoid taxes and a potential for unintended consequences that inadvertently outlaw something Congress never intended to touch. This growing complexity makes it more and more difficult for either companies or lawmakers to forecast the ultimate effects of new tax laws.
Megan McArdle, “We Don’t Need a Corporate Income Tax”, Bloomberg View, 2014-07-16.
Comments Off on QotD: The corporate tax game
March 11, 2015
December 20, 2014
QotD: When it’s steam engine time
Ridcully poked at his pipe with a pipe cleaner and said, “Ye-es, that is a conundrum. Surely the steam engine cannot happen before it’s steam-engine time? If you saw a pig, you would, I think, say to yourself, well, here’s a pig, so it must be time for pigs. You wouldn’t question its right to be there would you?”
“Certainly not,” said Lu-Tze. “In any case, pork gives me the wind something dreadful. What we know is that the universe is never-ending story that, happily, writes itself continuously. The trouble with my brethren in Oi Dong is that they are fixated on the belief that the universe can be totally understood, in every particular jot and tittle.”
Ridcully burst out laughing. “Oh, my word! You know, my wonderful associate Mister Ponder Stibbins appears to have fallen into the same misapprehension. It seems that even the very wise have neglected to take notice of one rather important goddess … Pippina, the lady with the Apple of Discord. She knows that the universe, while it requires rules and stability, also needs just a tincture of chaos, the unexpected, the surprising. Otherwise it would be a mechanism — a wonderful mechanism, ticking away the centuries, but with nothing different happening. And so we may assume that the loss of balance will be allowed this time and the beneficent lady will decree that this mechanism might yield wonderful things, given a chance.”
“For my part, I would like to give it a chance,” said Lu-Tze. “Serendipity is no stranger to me. I know the monks have been carefully shepherding the world, but I rather think they don’t realize that the sheep sometimes have better ideas. Uncertainty is always uncertain, but the difficulty with people who rely on systems is that they begin to believe that nearly everything is in some way a system and therefore, sooner or later, they become bureaucrats.”
Terry Pratchett, Raising Steam, 2013.
Comments Off on QotD: When it’s steam engine time
May 14, 2014
Not fewer entrepreneurs – fewer resources for entrepreneurs
This image showed up in a post at Coyote Blog a couple of days ago, and it’s an indication of the decline in new business formation in the United States:
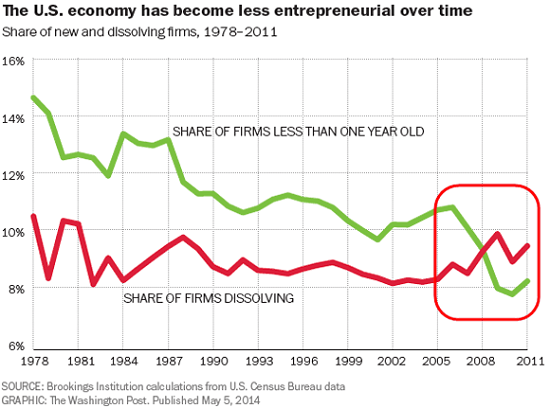
Increasing bureaucracy — especially at the state level — undoubtedly contributes to that depressing chart, but it’s far from the whole story:
Home equity has historically been an important source of capital for small business formation. My first large investment in my company was funded with a loan that was secured by the equity in my home. What outsiders may not realize about small business banking nowadays is that it is nothing like how banking is taught in high school civics. In that model, the small business person goes to her local banker and presents a business plan, which the banker may fund if they think it is a good risk.
In the real world, trying to get such an unsecured loan from a bank as a small business will at best result in laughter. My company is no longer what many would call “small” — we will do millions in revenue this year. But there is no way in the world that my banker of over 10 years will lend to my business unsecured — they will demand some asset they can put a lien on. So we can get financing of equipment purchases (as a capital lease on the equipment) and on factored receivables and inventory. But without any of that stuff, a new business that just needs cash for startup cash flow is out of luck — unless the owner has a personal asset, typically a house, on which the banker can place a lien.
So, without home equity, one of the two top sources of capital for small business formation disappears (the other top source is loans from friends and family, which one might also expect to dry up in a tough economy).
Comments Off on Not fewer entrepreneurs – fewer resources for entrepreneurs
May 9, 2014
QotD: Real history and economic modelling
I am not an economist. I am an economic historian. The economist seeks to simplify the world into mathematical models — in Krugman’s case models erected upon the intellectual foundations laid by John Maynard Keynes. But to the historian, who is trained to study the world “as it actually is”, the economist’s model, with its smooth curves on two axes, looks like an oversimplification. The historian’s world is a complex system, full of non-linear relationships, feedback loops and tipping points. There is more chaos than simple causation. There is more uncertainty than calculable risk. For that reason, there is simply no way that anyone — even Paul Krugman — can consistently make accurate predictions about the future. There is, indeed, no such thing as the future, just plausible futures, to which we can only attach rough probabilities. This is a caveat I would like ideally to attach to all forward-looking conjectural statements that I make. It is the reason I do not expect always to be right. Indeed, I expect often to be wrong. Success is about having the judgment and luck to be right more often than you are wrong.
Niall Ferguson, “Why Paul Krugman should never be taken seriously again”, The Spectator, 2013-10-13
Comments Off on QotD: Real history and economic modelling
February 26, 2014
“The Up Side of Down: Why Failing Well Is the Key to Success” (featuring the author, Megan McArdle)
Published on 25 Feb 2014
Featuring the author Megan McArdle, Columnist, Bloomberg View; with comments by Brink Lindsey, Vice President for Research, Cato Institute; moderated by Dalibor Rohac, Policy Analyst, Center for Global Liberty and Prosperity, Cato Institute.
Nobody likes to fail, yet failure is a ubiquitous element of our lives. According to Megan McArdle, failing often — and well — is an important source of learning for individuals, organizations, and governments. Although failure is critical in coping with complex environments, our cognitive biases often keep us from drawing the correct lessons and adjusting our behavior. Our psychological aversion to failure can compound its undesirable effects, McArdle argues, and transform failures into catastrophes.
Video produced by Blair Gwaltney.
Comments Off on “The Up Side of Down: Why Failing Well Is the Key to Success” (featuring the author, Megan McArdle)
September 20, 2013
The IPCC’s new, more cautious tone
In The Spectator, a muted tone of “we told you so” about the upcoming IPCC report:
Next week, those who made dire predictions of ruinous climate change face their own inconvenient truth. The summary of the fifth assessment report by the Intergovernmental Panel on Climate Change (IPCC) will be published, showing that global temperatures are refusing to follow the path which was predicted for them by almost all climatic models. Since its first report in 1990, the IPCC has been predicting that global temperatures would be rising at an average of 0.2° Celsius per decade. Now, the IPCC acknowledges that there has been no statistically significant rise at all over the past 16 years.
It is difficult to over-emphasise the significance of this report. The IPCC is not simply a research body making reports and declarations which are merely absorbed into political debate. Its word has been taken as gospel, and its research has been used to justify all manner of schemes to make carbon-based energy more expensive while subsidising renewable energy.
The failure of its predictions undermines the certainties which have been placed upon the science of climate change. Previous IPCC reports — and much of the debate over how to react to them — have appeared to treat the Earth’s climate as if it were a domestic central heating system, with carbon emissions analogous to the dial on the thermostat: a small tweak here will result in a temperature rise of precisely 0.2°C and so on. What is clear from the new IPCC report is that the science is not nearly advanced enough to make useful predictions on the future rise of global temperatures. Perhaps it never will be.
Some climate scientists themselves, to give them credit, have admitted as much. Their papers now incorporate a degree of caution, as you would expect from genuine scientists. The problems arise when the non-scientists leap upon the climate change bandwagon and assume that anything marked ‘science’ must be the final word. As the chemist and novelist C.P. Snow once warned in his lecture about the ‘two cultures’, you end up in a situation where non-scientists use half-understood reports to silence debate — not realising that proper science welcomes refutation and is wary of the notion of absolute truths.
Comments Off on The IPCC’s new, more cautious tone